Stock (Symbol) |
Grainger (GWW) |
Stock Price |
$235 |
Sector |
| Retail & Travel |
Data is as of |
| May 2, 2016 |
Expected to Report |
| Jul 19 |
Company Description |
 W.W. Grainger, Inc. is a distributor of maintenance, repair and operating (MRO) supplies and other related products and services. The Company offers its products and services to businesses and institutions in the United States and Canada, with presence also in Europe, Asia and Latin America. Grainger is a distributor of industrial and safety supplies that distributes tools, fasteners, safety supplies, instruments, welding and shop equipment, among others. Other businesses include Zoro, the single channel online business in the United States, and operations in Europe, Asia and Latin America. The Company provides customers with a range of options for finding and purchasing products, utilizing sales representatives, contact centers, direct marketing materials, catalogs and e-commerce. Source: Thomson Financial |
Sharek’s Take |
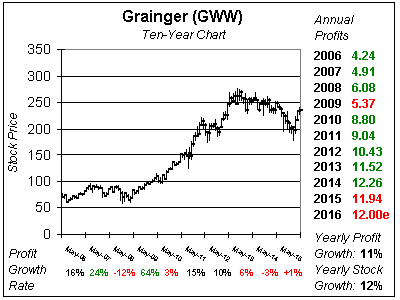
 Grainger’s (GWW) stock has made a valiant climb off its recent lows, and I just don’t understand why. GWW had been on a one-way ticket down from around $250 to $185 as profit growth went away due to (1) a lackluster economy (2) less business from struggling oil companies (3) competition from the Internet and (4) a strong dollar. As of this writing, only the dollar issue is waning away yet the stock has surged to $235. Grainger is the leading supplier for maintenance supplies in North America and sells motors, power transmission products, test instruments, lab supplies, power tools, outdoor equipment, as well as janitorial supplies. GWW is a safe stock. Management pays a dividend that has increased for 44 consecutive years (since 1972), buys back stock, purchases other supply stores, and invests in technology to spur Internet sales. Unfortunately online sales come with lower profit margins — as well as competition — and this is showing up in the numbers. Last qtr GWW had 3% profit growth on 3% sales growth. Profits haven’t grown on an annual basis since 2014, yet the stock has a P/E of 20. Now Grainger is a good solid company, but the stock had a P/E in the teens prior to 2013 when profits were growing around 10% a year. Estimates are for profits to increase an average of 2% the next four qtrs, and I feel this stock is only appropriate for large trust funds which need high safety and sacrifice growth to achieve it. |
One Year Chart |
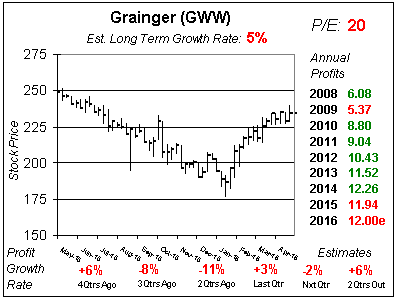 These numbers along the bottom don’t look good, and Estimates show -2%, 6%, 0% and 4% growth ahead. GWW has beaten the street soundly the past 22 qtrs so maybe it can keep that going as the weaker dollar should help things going forward. This stock made a huge jump off its lows, which I don’t quite understand. When GWW was $185 the stock sold for around 16x earnings which seems appropriate. |
Fair Value |
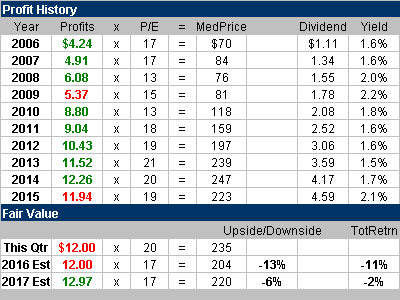 Notice that this company was growing profits consistently when the stock had a P/E in the teens. Now we are getting almost no profit growth yet GWW sells for 20x earnings. My Fair Value is 17x earnings or $204 a share. |
Bottom Line |
 Grainger’s profit estimates had decreased for seven consecutive qtrs before rising this qtr. But the numbers still look weak going forward and at 20x earnings this stock is rich. Still, this is a safe solid stock with the ability to provide total returns in excess of 10% a year if the environment is right, thus it stays on my radar. This stock is always appropriate for large trust funds that value safety and diversity. |
Power Rankings |
Growth Stock Portfolio
N/AAggressive Growth Portfolio N/AConservative Stock Portfolio N/A |
