Stock (Symbol) |
United Health (UNH) |
Stock Price |
$118 |
Sector |
| Healthcare |
Data is as of |
| October 22, 2015 |
Expected to Report |
| N/A |
Company Description |
 UnitedHealth Group Incorporated is a health and well-being company. The Company’s business platforms include UnitedHealthcare and Optum. UnitedHealthcare provides health care benefits to various customers and markets. Optum is a health services business serving the health care marketplace, including payers, care providers, employers, Governments, life sciences companies and consumers. The Company’s business platforms have four segments: UnitedHealthcare, OptumHealth, OptumInsight and OptumRx. OptumHealth is a health and wellness business serving the physical, emotional and financial needs of individuals. OptumInsight provides technology, operational and consulting services to participants in the health care industry. OptumRx is a pharmacy benefit manager. Purchased Catamaran 3/30/15. Source: Thomson Financial |
Sharek’s Take |
 Last qtr I complained that United Health (UNH) had jumped from $80 to $119 — a 50% move — when profit growth only averaged 16% the past four qtrs. Since then UNH’s P/E has been basing, and now that I am calculating the P/E on 2016 earnings instead of 2015’s, the P/E has fallen to 16. There’s a couple of reasons for the lag. Profit growth was just 1% last qtr, and is expected to be 1% this qtr before bouncing to 16% 2 qtrs out. There’s also money being taken out of the Healthcare sector from fund managers as a handful of stocks in the sector have warned (money managers have been overweight healthcare, myself included). UNH is expected to grow profits 13% long-term, pays out 30% of profits to pay a dividend of 1.75%, and management buys back stock in addition to acquiring other companies, like pharmacy benefit manager Catamaran. Catamaran is a great company I owned for many years and should add $0.30 to profits this year. I will add UNH to my Conservative Growth Portfolio. This is certainly worth 16x earnings, but with momentum lost for now this buy is more for the long-term. |
One Year Chart |
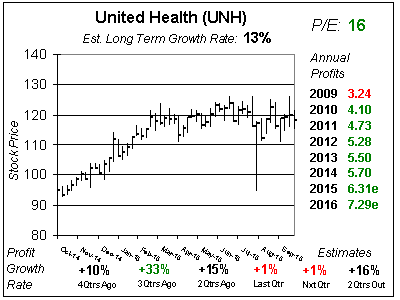 Here in the one-year chart you can clearly see the 1% profit growth that’s partially to blame for the stock’s weak performance lately. Still, I feel UNH needed a breather as the previous run was from $25 to $125. Another reason for the weakness could be the fact UNH had estimates decline ever-so-slightly this qtr. UnitedHealth has clean financials. All the EPS figures in its annual reports match year-to-year and also match Thomson Financial. I trust the company. |
Fair Value |
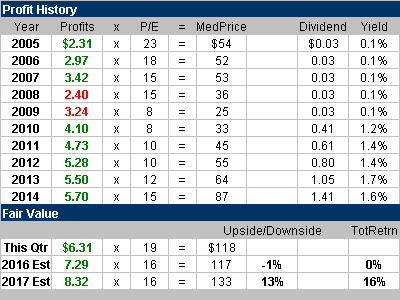 UNH has a 16 P/E and that’s what I think it should be. The stock was $118 when these charts and tables were compiled and I feel the stock has a 2016 Fair Value of $117. Like many stocks, UNH has gotten ahead of itself and need to digest some previous gains. |
Bottom Line |
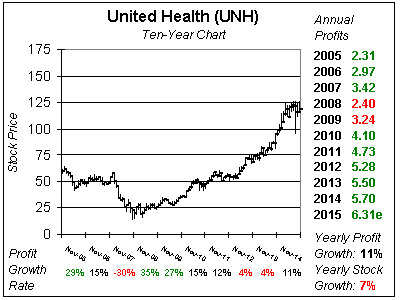 Although the ten-year chart doesn’t looks so hot, the company had good results outside the 2008-2009 years. The real problem with UNH was it had a 23 P/E in 2005 and that was too high. Now the 16 P/E is just right. I will add UnitedHealth to the Conservative Growth Portfolio. Although its selling around its 2016 Fair Value I think this is a quality stock to collect then hold on to for the long-term, but since the UNH is selling at next year’s Fair Value it ranks 27th of 30 stocks in the Power Rankings. |
Power Rankings |
Growth Stock Portfolio
N/AAggressive Growth Portfolio N/AConservative Stock Portfolio 27 of 30 |
