Stock (Symbol) |
DR Horton (DHI) |
Stock Price |
$174 |
Sector |
| Industrials & Energy |
Data is as of |
| July 21, 2024 |
Expected to Report |
| November 5 |
Company Description |
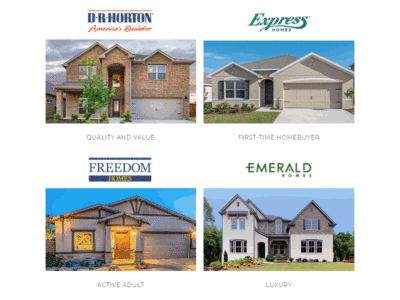 D.R. Horton is engaged in the acquisition and development of land and the construction and sale of residential homes. Its segments include homebuilding, Forestar lot development, financial services, and rental operations. Its homebuilding business operates in 106 markets across 33 states. Its Forestar lot development segment operates in 53 markets across 21 states. Its financial services segment provides mortgage financing and title agency services to homebuyers in many of the Company’s homebuilding markets. Its rental segment consists of multi-family and single-family rental operations. The multi-family rental operations develop, construct, lease and sell residential rental properties. The single-family rental operations primarily construct and lease single-family homes within a community and then market each community for a bulk sale of rental homes. Its brands include Emerald Homes, Express Homes and Freedom Homes. Source: Refinitiv |
Sharek’s Take |
 Homebuilder D.R. Horton (DHI) isset to be a big benefactor of lower morgate rates! The Federal Reserve is expected to begin lowering interest rates in September as inflation has settled down, and that means lower morgage rates are onthe way too. In fact, morgage rates have been on the decline since April. So far in 2024, the 30-year fixed rate has gone from 6.82% to a hiogh of 7.52 in April, and has since settled back to 6.82% (source: Morgage News Daily). Lower rates will not only spur demand for new homes, but will also help DR Horton’s profits as the company has been paying to provide lower rates to its consumers (morgage rate buydowns) in addition to adding free perks on new homes. In last qtr’s earnings call, DHI management stated supply of new and existing homes at affordable prices is limited, with favorable demographics supporting housing demand. But, one warning sign just popped up. Parts of Texas and Florida markets have a slew of inventory build. This could mean slowing demand, and perhaps markdowns of inventory. Also, multifamily housing starts dropped 20% in March to the lowest levels since April 2020. Founded in 1978 in Fort Worth Texas, DH Horton is the largest home-building company in the United States. The company constructs and sells homes across 33 states. Homes range in size from 1,000 square feet to 4,000 square feet and are priced between $200,000 to more than $1 million. In 2023 the company closed 84,917 homes, 5860 rental homes, and 2122 multi-family rental properties. The company also offers mortgages, title services, and insurance for home buyers. Substantially all the company’s land development and home construction are performed by subcontractors. DHI employs construction superintendents to coordinate subcontractor activities and interact with home buyers. As of December 31, 2023 the company had approximately 600,000 lots, of which 24% were owned and 76% were controlled through purchase contracts. The use of purchase contracts is a positive development in the homebuilding industry, and it doesn’t saddle the builder with expensive inventory. Here’s a run-down of DHI’s brands:
Management focuses on making money in all its communities and has strong cash flow. With plenty of cash and low debt, it can make smart financial decisions. The company plans to keep investing wisely to grow its value and give back to shareholders by increasing dividends and buying back shares. DR Horton stock has a low P/E, but home builders always do. DHI has an Estimated Long-Term Growth Rate of 6% but I feel this is a 10% profit grower. The stock also yields a little less than 1%. Management spent $1.2 billion on stock buybacks in fiscal 2023. DR Horton will be purchased today in the Conservative Stock Portfolio. |
One Year Chart |

DHI stock poppe after earnings, and has continue to rise since this chart was made last week on. Charts and tables were donwe on 7/21 when DHI was $174. Today, 7/30, the stock is $181. Notice in the one year chart DHI broke out to a 52 week high. Investors sense good things to come. The Estimated Long-Term Growth Rate is only 6%. I think this stock is around 10-12% grower. But the P/E of only 12 makes this stock a value. Qtrly profit growth is poor. I imagine that will accelerate with lower rates (and the company not having to spend on morgage rate buydowns). |
Earnings Table |
 Last qtr, D.R. Horton posted 5% profit growth and beat expectations of -3% growth. Revenue increased 2% versus estimates of 1% growth. Gross profit margin on home sales was 24.0%, up from 23.3% a year ago due to effective cost management strategies. Other stats include:
Annual Profit Estimates are up this qtr. Management expects to close between 24,000 and 24,500 homes next quarter. Qtrly Estimates call for profit growth of -7%, 3%, 7%, and 8% in the next 4 qtrs. Analysts estimate next qtr’s revenue growth will be -3%. Quarterly profit estimates are fair. |
Fair Value |
 DHI should have a P/E of 12 in my opinion. My 2024 Fair Value is $190 a share, which the stock is now approaching. Upside is good when we look to 2025. |
Bottom Line |
 DR Horton (DHI) has a very nice ten-year chart, but the stock has been a laggard in past periods. What’s not shown here is in mid-2005 the stock peaked around $40 and didn’t hit All-Time highs again until 2017 (which you can see in the middle of this chart). DR Horton is set to benefit from lower morgage rates. In addition, money has been flowing out of tech stocks recently, and investors are looking for somewhere new to invest. Homebuilders have been moving higher, and I think the sector is up-and-coming once again. DHI will nbe added to the Conservative Growth Portfolio today and rank 9th in the Power Rankings. |
Power Rankings |
Growth Stock Portfolio
N/AAggressive Growth Portfolio N/AConservative Stock Portfolio 9 of 24 |
