Stock (Symbol) |
Dutch Bros (BROS) |
Stock Price |
$58 |
Sector |
| Retail & Travel |
Data is as of |
| June 2, 2026 |
Expected to Report |
| August 4 |
Company Description |
 Dutch Bros Inc. is an operator and franchisor of drive-thru shops that focus on serving hand-crafted beverages. The Company offers a variety of customizable cold and hot beverages to its customers. Its hand-crafted beverage offerings include hot and cold espresso-based beverages, cold brew coffee products, Dutch Bros. Blue Rebel energy drinks, tea, lemonade, smoothies and other beverages. Its other beverages include Iced Tiger’s Blood Lemonade, Birthday Cake Frost, Blended Aftershock Rebel, Golden Eagle Freeze, Hot Annihilator, Iced Caramelizer and Iced Electric Berry Rebel. It also offers private reserve coffee sourced through their in-house coffee roasting facility and extracted using La Marzocco machines. It operates approximately 538 shops in 12 states, of which 271 are Company-operated shops and 267 franchise shops. Its shops are located in Arizona, California, Colorado, Idaho, Kansas, Nevada, New Mexico, Oklahoma, Oregon, Texas, Utah, and Washington. (Source: Refinitiv) |
Sharek’s Take |
 Last quarter, Dutch Bros (BROS) delivered Impressive results with revenue up a robust 31% as same shop sales increased 8%. Company owned same shop sales increased an impressive 11% year-over-year. Note, of the 41 shops BROS opened last qtr, 33 were company owned. But profits grew a modest 14% as the company had tough comparisons from the year-ago period when profits surged 56%. The company remains firmly in expansion mode and is investing heavily in growth. As I just mentioned, it opened 41 new shops last quarter, bringing its total store count to 1,177. Dutch Bros also completed the rollout of its food program across 485 company-operated and franchised locations, further enhancing its sales-driving initiatives. Given its performance last quarter, management raised its 2026 guidance, projecting approximately 26% revenue growth and ~5% same-store sales growth. This will be supported by the ongoing expansion plans, with the company targeting at least 185 new store openings in 2026, reinforcing its long-term unit expansion strategy and growth trajectory. Dutch Bros is a quick-service drive-thru coffee shop chain that serves up iced coffee, energy drinks, and a few snacks. Dutch Bros started began when two brothers who were third-generation dairy farmers bought a double-head espresso machine and opened a pushcart espresso bar in 1992 on the side of the railroad tracks in the state of Oregon. They were quickly making more than $100 a day, and put the money back into the business until one pushcart became five. The company had its first franchise in 2000 and has since grown into an operation with 1136 coffee shops, as of December 31, 2025. Of the 1136 shops, 811 are company owned and 325 are franchised, including the recently acquired clutch coffee shops. With the company’s current expansion plans, management believes it is in line with its goal to reach 2029 shops by 2029. Here’s some more interesting points about the company:
Dutch Bros is a compounding story, as management has plans to grow from 1000 shops to 4000 during the next 10 to 15 years. Analysts give the stock a high Estimated Long-Term Growth Rate (Est. LTG) of 34% a year. I imagine profits might have the ability to climb 30-35% a year in the long-run. BROS is in my Growth Portfolio and Focus List. |
One Year Chart |
 Note: BROS was $58 when thes echarts & tables were done on 6/2. Today, 6/22, the stock is $69. Stocks have four stages of a run:
BROS is now in Stage 2. The 62 P/E is high, but the company is young and growing profits briskly. I don’t feel the stock is overvalued, and I’ll explain why later. The Est. LTG is 34%, which I feel is accurate. Quarterly profit growth has been erratic this past year. |
Earnings Table |
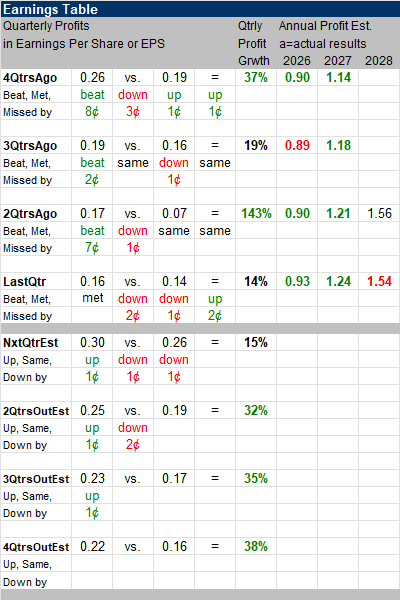 Last quarter, Dutch Bros met estimates of 14% profit growth. Revenue increased 31% year-on-year and beat estimates of 27%. Systemwide same-shop sales rose 8%, while company-owned same-shop sales grew 11%. Company-operated shop margins decreased to 28.3% from 29.8% a year ago.
Annual Profit Estimates are mixed last quarter. Management increased its 2026 guidance, projecting approximately 26% revenue growth and 4-6% same-store sales growth. Total systemwide store openings are expected to reach at least 185. Quarterly Profit Estimates for the next 4 quarters are 15%, 32%, 35%, 38% growth. Analysts think BROS’ revenue will grow 26% next quarter. |
Fair Value |
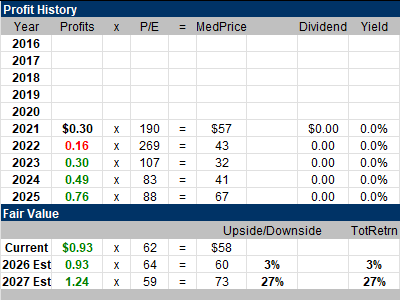 This is too young of a company to price the stock on a P/E basis, so I will use price-to-sales. This quarter, with the stock at $58, it sells for 5x 2026 annual revenue estimates. My Fair Value is 5x revenue. Here are my price estimates for 2026 and 2027: Current quarter: 2026 Fair Value: 2027 Fair Value: |
Bottom Line |
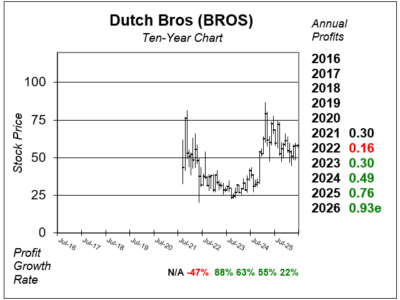 Dutch Bros (BROS) garnered a lot of attention when it debuted as the shares opened at $33 in August 2021. Within two months the shares pushed past $80. Then the stock tumbled lower. Notice profits declined in 2022. At the time, BROS had high goods inflation and high labor costs to deal with. During 2022-2024, the stock built a saucer pattern, and broke out in November 2024 when it surged past $35 after earnings were released. Today, this ten-year chart looks sloppy. Dutch Bros is a nice young company with a bright future. Results were very good this quarter. Restaurants have had a tough time in general this past year, and I think this stock is a leader of the sector. BROS ranks 11th in the Growth Portfolio Power Rankings. The stock bumps up from 12th to 11th in the Focus List Power Rankings. I added the stock to this portfolio last qtr. |
Power Rankings |
Growth Stock Portfolio
11 of 30Focus List 11 of 18Conservative Stock Portfolio N/A |
