Stock (Symbol) |
Visa (V) |
Stock Price |
$95 |
Sector |
| Financial |
Data is as of |
| May 30, 2017 |
Expected to Report |
| Jul 19 |
Company Description |
 Visa Inc. is a payments technology company. The Company is engaged in operating a processing network, VisaNet, which facilitates authorization, clearing and settlement of payment transactions across the world. The Company provides its services to consumers, businesses, financial institutions and governments in more than 200 countries and territories for electronic payments. Source: Thomson Financial |
Sharek’s Take |
 Visa (V) is clicking on all cylinders. The credit card processor has a slew of catalysts pushing up sales and profits, notably Visa Europe, Costco and USAA. Last year Visa acquired Visa Europe, took Costco’s credit card business from AMEX, and took USAA’s business from MasterCard. USAA is the nation’s 10th largest credit card issuer. These new deals have pushed profit growth beyond expectations, but management says the company is beating expectations due to global economic growth. International and e-commerce is where the growth opportunity lies for Visa, with cross-border growth being in the double-digit range the past three qtrs. The global opportunity to digitize cash and check is enormous — Visa CEO in an earnings call 2qtrs ago. Last qtr Visa executed a PayPal (Venmo?) partnership in Asia Pacific. This company is also a play on digital payments. Visa Checkout has 20 million people and 300,000 merchants enrolled. This stock is suitable for conservative investors and growth investors as well. V is a very safe stock that’s delivered more than 20% profit growth on average since it went public in 2008. Last qtr management spent $400 million on dividends and $1.7 billion buying back its own stock. Profits have grown an average of 26% a qtr the past three qtrs, but that growth might come down a bit after next qtr as results from these new deals have boosted results the past 3 qtrs. Long-term, the Est. LTG is 17% per year in addition to a 1% dividend yield. With a P/E of 28 the stock’s not on sale, but I think this exceptional momentum carries it higher. Visa has 20% upside to my 2018 Fair Value of $114. |
One Year Chart |
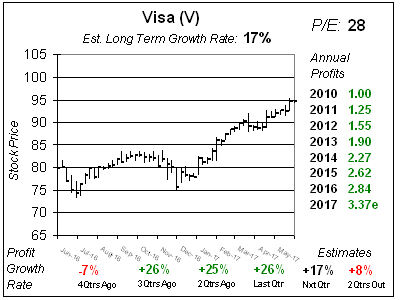 Last qtr V delivered sales growth of 23% and profit growth of 26%. Analysts expected 16% profit growth. Note profit growth has been strong for 3 qtrs now, and results could slow 2QtrsOut. Estimates are for 17%, 8%, 13% and 13% profit growth the next 4 qtrs, but my guess is V will deliver 20% growth the next year. The Est. LTG of 17% is exceptional for a safe stock such as this. |
Fair Value |
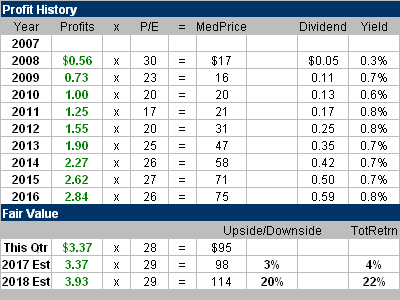 Visa is considered to be a 17% grower, and typically has a P/E of 25-28 because of its consistency in growing profits each year. Now profit growth is 26%, so I could take my Fair Value P/E to 32 or so — only to take it back down if or when profit growth slows. So I’ll stick with a Fair Value of 29x earnings, which still gives the stock good upside for the next year. |
Bottom Line |
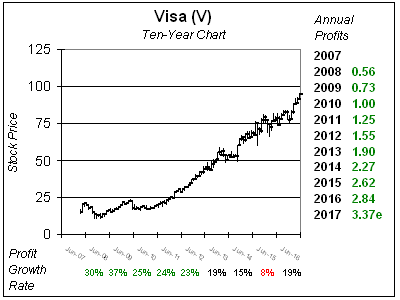 Visa is clicking on all cylinders, but we need to stay level-headed. Results have been amazing the past three qtrs due to some great deals Visa landed. But will profit growth fall back to the 17% level two qtrs from now? If so a P/E of 28 is reasonable My guess is V could still grow 20%, and I envision gains beyond my expectations. Either way this should be a top holding in any stock investor’s portfolio. V ranks 12th in the Growth Portfolio and Aggressive Growth Portfolio Power Rankings and 3rd in the Conservative Portfolio Power Rankings. |
Power Rankings |
Growth Stock Portfolio
12 of 30Aggressive Growth Portfolio 12 of 15Conservative Stock Portfolio 3 of 34 |
