Stock (Symbol) |
Stryker (SYK) |
Stock Price |
$109 |
Sector |
| Healthcare |
Data is as of |
| May 2, 2016 |
Expected to Report |
| Jul 21 – Jul 25 |
Company Description |
 Stryker Corporation is a medical technology company. The Company offers a range of products and services in Orthopaedics, Medical and Surgical, and Neurotechnology and Spine, which help improve patient and hospital outcomes. Source: Thomson Financial |
Sharek’s Take |
 Last qtr I wrote “Stryker (SYK) is growing profits around 8% to 10% right now”. Well that was then, and now the manufacturer of replacement joints, surgical equipment and hospital beds produced is expected to post its strongest profit growth since 2012. Profits jumped 12% last qtr helped by higher profit margins from new products and analysts estimate profits will grow 12% to 16% the next 4 qtrs. Stryker has compiled 36 straight years of record sales growth and is cash rich. The company uses its money wisely to buy back stock, pay a dividend of 1.4%, and make acquisitions. Recent buys have helped boost profit margins from 21% to 24% last qtr. Stryker is a safe stock that just kicked its profit growth up a notch, and that’s attracting investors. The only negative is the stock sells for 19x earnings, which is around its high since 2008. I will add SYK to the Conservative Growth Portfolio as the stock is timely. |
One Year Chart |
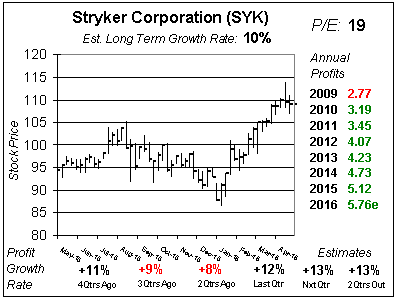 Stryker produced 12% profit growth on 5% sales growth last qtr. The company beat the street as analysts had expected 8% profit growth. The good results caused estimates to rise across the board. 2016’s profit estimate increased from $5.61 to $5.76 and 2017’s from $6.12 to $6.37 — nice. Estimates for the next 4 qtrs are now 13%, 13%, 12% and 16%. Those are solid, steady numbers. The Est. LTG is 10% a year and if you tack on the 1% yield that would be an estimated total annual return of 11% a year (hypothetically). |
Fair Value |
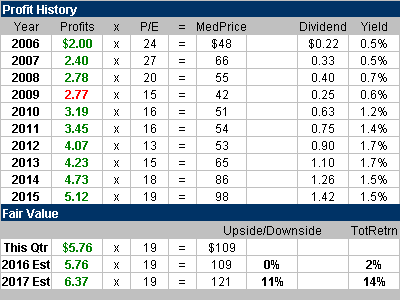 I’m taking my Fair Value up from 17x earnings to 19x. Unfortunately the stock is selling for 19x earnings now, so Stryker’s not “on sale” but estimates did rise and could rise again in the future. |
Bottom Line |
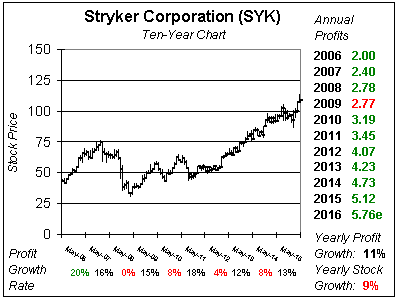 Stryker stock hasn’t grown as much as its profit have during the last decade because the P/E was a little too high ten years ago. But after the stock digested its prior gains its been on a steady road higher. Although the potential upside isn’t great, this is a good buy-and-hold stock for conservative accounts. And accelerated profit growth will surely catch the attention of mutual fund managers. I will add SYK to the Conservative Portfolio where it will rank 27th of 36 stocks in the Power Rankings. |
Power Rankings |
Growth Stock Portfolio
N/AAggressive Growth Portfolio N/AConservative Stock Portfolio 27 of 36 |
