Stock (Symbol) |
Sea (SE) |
Stock Price |
$91 |
Sector |
| Retail & Travel |
Data is as of |
| June 19, 2026 |
Expected to Report |
| August 10 |
Company Description |
 Sea Limited, through its subsidiaries, operates three core businesses of e-commerce, digital financial services, and digital entertainment, known as Shopee, SeaMoney and Garena. Garena offers mobile and personal computer online games and develops mobile games for the global market. It offers e-sports and provides access to other entertainment content and social features, such as live-streaming of gameplay, user chat, and online forums. Shopee is a mobile-centric, social-focused marketplace. It provides users a shopping environment with integrated payment, logistics infrastructure, and seller services. SeaMoney provides digital financial services and products, including mobile wallet services, payment processing, credit, banking, and Insurtech. It operates in Indonesia, Taiwan, Thailand, Singapore, Malaysia, and the Philippines. Source: Refinitiv. |
Sharek’s Take |
 Sea (SEA) is prioritizing growth investments over near-term profit expansion as management sees significant opportunities across e-commerce, fintech, and digital entertainment. Last qtr, the company reported 3% profit growth on 47% revenue growth, with all three segments still growing revenue at solid rates (Shopee +44%, Monee +58%, Garena +41%). Management stated the lower profit growth was driven by increased spending on delivery, fulfillment, ShopeeVIP memberships, and user acquisition. Many of thesse investments are already showing results, with instant deliver orders growing more than 35% year-over-year, fulfillment orders rising 25% sequentially, and ShopeeVIP subscribers surpassing 10 million. Management believes these investmenst will strengthen Shopee’s competitive position and support long-term growth. And profit growth is expected to turn up during the next four quarters, with 23%, 56%, 56%, and 64% growth expected from analysts. Yet the stock stays near its lows, as investors worry that heavy spending to fight off rivals like TikTok Shop and MercadoLibre will keep competition high and margins low. Sea is an Internet company based out of Singapore that is composed of a video game platform, an e-commerce store, and an e-wallet service. The company’s an affiliate of Tencent. Tencent is China’s largest and most used internet service portal as well as the leading video game company in China. Sea’s market is Southeast Asia (70% of 2025 revenue), Latin America (20%), Rest of Asia (9%) and Rest of the World (1%). Here’s a quick video of Sea. Sea operates three businesses — Shopee, Monee and Garena.
Sea is a stock I used to own years ago. It went on a quick magnificent run higher, then had a dramatic decline as profits didn’t materialize as expected. Today, the company is profitable again. SE has an Estimated Long-Term Growth Rate (Est. LTG) of 16%, which is way lower than I thought it should be. SE is part of the Growth Portfolio. |
One Year Chart |
 SE has been in a clear downtrend, losing around half its value during the past year. This chart is ugly. The Est. LTG of 16% is down big time from 65% last quarter. But this is a 3-5 year profit growth estimate. Profits are coming off a small base, so fast growth is easy. With a P/E of 27, SE is currently undervalued in my opinion. My Fair Value is a P/E of 35. Quarterly profit growth was very weak last qtr. But Estimates look good. |
Earnings Table |
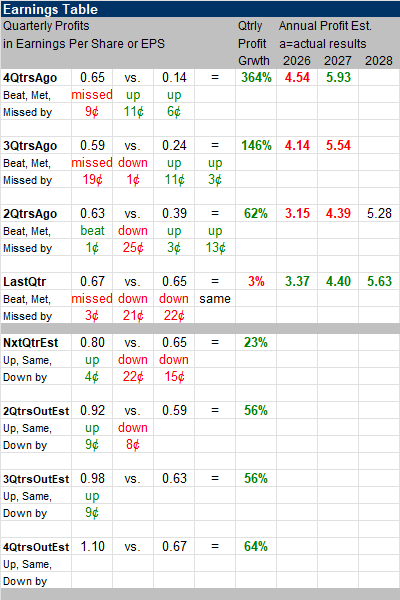 Last quarter, Sea delivered a profit growth of 3% and missed expectations of 8% growth. Last qtr’s profit growth was expected to be 74% a few quarters ago. For the company to deliver just 3% is weak. Revenue increased 47% year-over-year and beat estimates of 32%.
Annual Profit Estimates increased this qtr. For 2026, management guides for continued momentum, with Shopee expected to deliver approximately 25% GMV growth. Quarterly Profit Estimates for the next four quarters are 23%, 56%, 56%, and 64% growth. I’m happy to see these estimates increased for a change. Analysts estimate 32% revenue growth for next quarter. |
Fair Value |
|
2027’s Fair Value is $154 a share, giving the stock upside of 69% when we look further out. If I price the stock on a price-to-annual revenue basis, the stock sells for 2x 2026 revenue estimates. My Fair Value would be 3x revenue estimates, which is $149 for this year (+63%) and $181 for next year (+98%). |
Bottom Line |
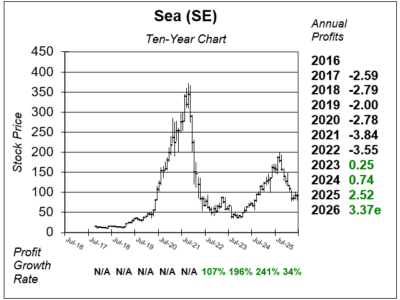 Sea (SE) is one of the world’s fastest growing companies. The stock has been one of the market’s best, then the worst, then best, and now worst. Sea is really under pressure from competition. The stock’s not right even though the numbers look great.. Sea ranks last in the Growth Portfolio Power Rankings. |
Power Rankings |
Growth Stock Portfolio
30 of 30Aggressive Growth Portfolio N/AConservative Stock Portfolio N/A |
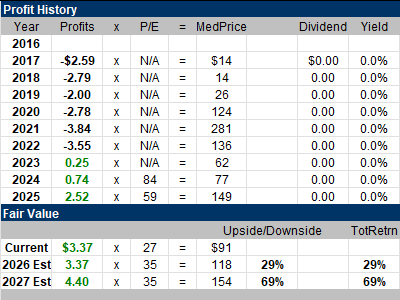 My Fair Value on this stock is a P/E of 35, or $118 a share, giving the stock upside of 29% from the recent quote of $91.
