Stock (Symbol) |
Oracle (ORCL) |
Stock Price |
$198 |
Sector |
| Technology |
Data is as of |
| December 22, 2025 |
Expected to Report |
| March 9 |
Company Description |

Oracle Corporation offers integrated suites of applications plus secure, autonomous infrastructure in the Oracle Cloud. The Company’s segments include cloud and license, hardware, and services. The cloud and license segment markets, sells and delivers a broad spectrum of enterprise applications and infrastructure technologies through its cloud and license offerings. The hardware segment provides a broad selection of enterprise hardware products and hardware-related software products including Oracle Engineered Systems, servers, storage, operating systems, virtualization, management and other hardware-related software and related hardware support. The services segment helps customers and partners maximize the performance of their investments in Oracle applications and infrastructure technologies. Its products and services are delivered worldwide through a variety of flexible and interoperable IT deployment models. These models include on-premise, cloud-based and hybrid deployments. Source: Refinitiv |
Sharek’s Take |
 Oracle (ORCL) has become a big player in AI data centers, as its backlog of booked but yet to be billed revenue has ballooned at a startling rate the past two quarters. Remaining Performance Obligations (RPO) is the term used for short-term forward looking revenue for services that are yet to be delivered. During the past three qtrs, backlog (RPO) has gone from $138 billion to $455 billion and now $523 billion, driven by contracts signed with OpenAI, Meta, NVIDIA and others. To put this into perspective, ORCL did $57 billion in revenue in its last fiscal year, and now has a backlog around 10x that. Management made it clear that demand is not an issue, the challenge is building capacity fast enough to deliver already-signed contracts. Management said Oracle will fund this expansion using a mix of traditional debt, customer-supplied hardware, and supplier chip-leasing arrangements where chips are rented instead or purchased, which reduces upfront capital needs. Founded in 1977 and incorporated in 2005, Oracle is the world’s second-largest enterprise software company, known for its strong position in databases and cloud infrastructure. Oracle provides products and services that address enterprise information technology (IT) needs. It also offers professional services to assist its customers in technical tasks. Artificial Intelligence (AI) has two processes:
ORCL management has stated AI Inferencing will much, much larger than AI Training, as Inferencing will be used to run robotic factories, robotic cars, robotic greenhouses, biomolecular simulations for drug design, and much more. ORCL’s business segments are:
Oracle is now expected to have revenue surge over the next 3-5 years. ORCL did $57 billion in revenue last year. It’s now expected to do $221 billion a year by 2029 (Fiscal Year Ending May 2030). But the company is spending big to build infrastructure to support these added revenue. Cap Ex for this fiscal year is expected to be $35 billion. Looking ahead, analysts have an Estimated Long-Term Growth Rate of 19% on the stock. The P/E of 27 is reasonable. Last Fiscal Year (ending May 2025), management repurchased a total of $600 million of shares and paid out dividends of $4.7 billion. ORCL also has a dividend yield of 1%. ORCL is part of the Conservative Growth Portfolio and Growth Portfolio. |
One Year Chart |
 ORCL stock ran up strongly earlier in the year, topping near $320. but has been pulling back since as investors wonder about financing of these big buildouts. ORCL has a P/E of 27 this qtr, which is I think currently undervalued. My Fair Value is P/E of 35. More on this later. Notice the Est. LTG is 19%, same with 2QtrsAgo. That’s a pretty good figure for a conservative stock like this. Quarterly profit growth was strong LastQtr, although expectations for the next two qtrs are for only in mid-teens. |
Earnings Table |
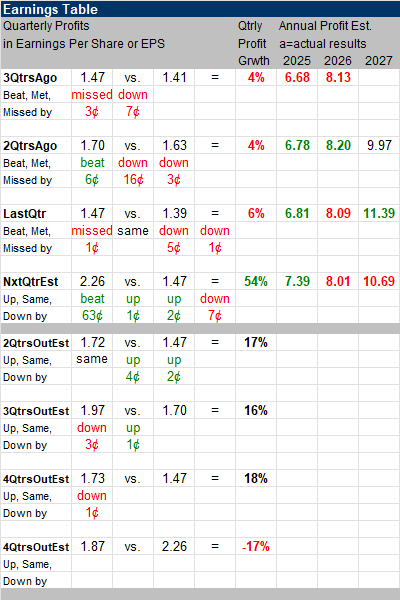 Last qtr, Oracle reported 54% profit growth and beat analyst estimates of 11%. Revenue increased 14% year-over-year andmissed analyst’s expectation of 15%. Operating margin was 42%, down from 43% a year ago.
Annual Profit Estimates are mixed this qtr. Qtrly Profit Estimates are for 17%, 16%, 18%, and –17% growth in the next 4 qtrs. Analyst think revenue will grow 20% next quarter. |
Fair Value |
|
My 2025 Fair Value is a P/E of 35, which equates to $259 a share. That’s upside of 30%. 2026 Fair Value sits at $280 a share, upside of 41%. Very Impressive! ORCL has a May 31 Fiscal Year end. I’m calling this current year 2025 because it has 7 months in it. Management calls this year Fiscal 2026. |
Bottom Line |
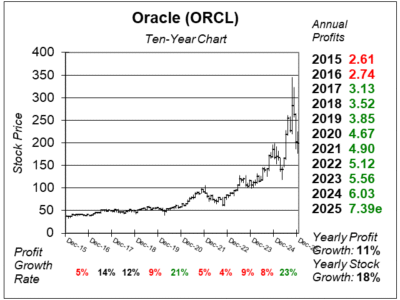 Oracle (ORCL) has been a strong performer duting the past five years. The recent spike shown here was due to the P/E expanding. ORCL stock has a bright future ahead as its AI datacenters roll in revenue. I like this stock moper than most investors do. The stock ranks 7th in the Conservative Growth Portfolio Power Rankings. ORCL moves from 18th to 15th in the Growth Portfolio Power Rankings. |
Power Rankings |
Growth Stock Portfolio
15 of 28Aggressive Growth Portfolio N/AConservative Stock Portfolio 7 of 18 |
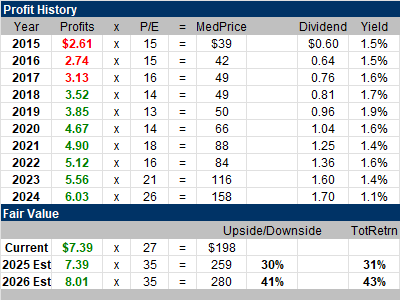 Notice this stock used to have a P/E between 13 and 18. This quarter the P/E is 27.
