Stock (Symbol) |
Five Below (FIVE) |
Stock Price |
$34 |
Sector |
| Retail & Travel |
Data is as of |
| January 10, 2016 |
Expected to Report |
| Mar 23 – Mar 28 |
Company Description |
 Five Below, Inc. is a specialty retailer offering a range of merchandise for teen and pre-teen customer. The Company offers a range of products, all priced at five dollars and below, including select brands and licensed merchandise across a range of categories, including Style, Room, Sports, Tech, Crafts, Party, Candy and Now. The Company operates 366 locations across 21 states. The Company’s stores have over 4,000 stock-keeping units (SKUs) across a range of categories. The Company’s product groups include leisure, fashion and home, and party and snack. Leisure includes items, such as sporting goods, games, toys, tech, books, electronic accessories, and arts and crafts. Fashion and home includes items, such as personal accessories, ‘attitude’ t-shirts, beauty offerings, home goods and storage options. Party and snack includes items, such as party and seasonal goods, greeting cards, candy and other snacks, and beverages. Source: Thomson Financial |
Sharek’s Take |
 Five Below (FIVE) is using the force to withstand the stock market’s wrath. The is a dollar store for kids and teens is selling Star Wars merchandise between $1 and $5 and this could be a catalyst for a solid qtr. Profits last qtr rose 33% on a 23% gain in sales and the next four qtrs look good as well with 25%, 25%, 31% and 25% profit growth expected. FIVE is holding up well in the current stock market crash, as investors see big growth opportunity on the horizon. FIVE ended 2014 with 366 stores, is expecting to add 70 more in 2015, and has a long-term opportunity of 1400 to 2000 locations. All-important same-store sales of 5% last qtr was a solid number, and indicative that business is good. The company is now gearing up for fitness, with $5 hand weights, fitness tracker watches, workout gear and sports bras. 100% of sales are in the U.S., so no F/X concerns, and the Chinese goods FIVE buys will now be cheaper to buy, which should improve profit margins. My Fair Value is $42 for 2016 and $51 for 2017 which is 26x earnings, a fair valuation as profits are expected to grow 27% on average the next 4 qtrs. |
One Year Chart |
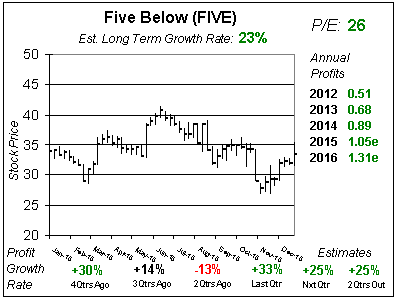 FIVE just started on what could be a solid run or profit growth. Last qtr profits jumped 33% on a 23% gain in sales, boosted by solid 5% growth in same store sales. Estimates show 25%, 25%, 31% and 25% profit growth the next 4 qtrs. The company has been meeting estimates or coming in a penny higher four straight qtrs, and annual estimates have remained steady during that time. The P/E of 26 is good as this company has an estimate long-term growth rate of 23%. |
Fair Value |
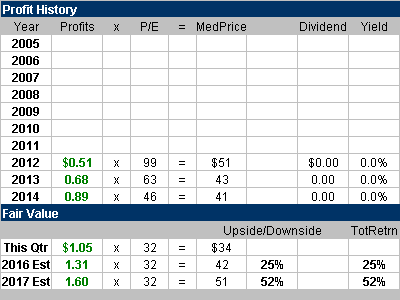 Five Below has had a rich valuation since it went public, and that P/E has come down a lot in three years. The stock now sells for 26x earnings, and I feel the P/E should be 32. Profits are expected to grow 25% in 2016, and annual estimates have remained steady for a year. How many companies can claim that? Upside to 2017’s Fair Value is 52%, which is indicative of a quality stock in a bear market. |
Bottom Line |
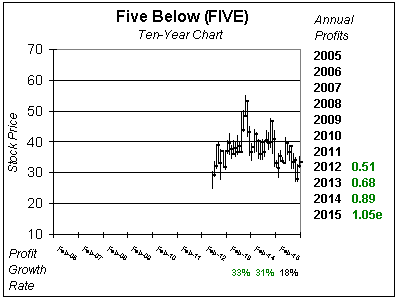 Five Below could quadruple its store count in the next 5-to-10 years, and perhaps the stock could go up four-fold as well. Further out, I foresee another dollar store acquiring FIVE. In the meantime profits are growing/expected to grow 25% to 33% per qtr. This is a good selection in the current marketplace as all sales come from the U.S. thus there are no foreign exchange issues. In fact, Chinese goods will be cheaper to acquire. Five Below ranks 19th of 37 stocks in the Growth Portfolio Power Rankings. |
Power Rankings |
Growth Stock Portfolio
19 of 37Aggressive Growth Portfolio N/AConservative Stock Portfolio N/A |
