Stock (Symbol) |
Booking Holdings (BKNG) |
Stock Price |
$5195 |
Sector |
| Retail & Travel |
Data is as of |
| May 12, 2025 |
Expected to Report |
| July 30 |
Company Description |
 Booking Holdings Inc. is a provider of travel and restaurant online reservation and related services. The Company offers its services through six consumer-facing brands: Booking.com, priceline.com, agoda.com, Rentalcars.com, KAYAK and OpenTable, Inc. (OpenTable). Through the Company’s brands, consumers can: book a range of accommodations, including hotels, motels, resorts, homes, apartments, bed and breakfasts, hostels, and other properties; make a car rental reservation or arrange for an airport taxi; make a dinner reservation; book a flight, cruise, vacation package, tour or activity. Consumers can also use its meta-search services to easily compare travel reservation information, such as airline ticket, hotel reservation, and rental car reservation information, from various online travel platforms at once. Booking.com offers accommodation reservation services for approximately 2,373,000 properties in over 220 countries and territories, and in over 40 languages. Source: Refinitiv |
Sharek’s Take |
 Booking (BKNG) is a money printing machine as it grows profits briskly on moderate profit growth. Last quarter, profits grew 22% on a modest 8% increase in revenue, and a 7% gain in gross bookings. While revenue increased 8%, operating expenses rose just 2%. That’s the power of an ecommerce platform. The company’s global presence allowed it to offset weaker US travel trends with stronger demand in Europe, Asia, and corridors like Canada to Mexico. The Genius loyalty program, now with over 30% of active users in its higher tiers, contributed to stronger repeat booking behavior. At the same time, BKNG advanced its connected trip strategy—aimed at integrating flights, hotels, activities, and more—while expanding the use of AI to improve search results, automate support, and personalize the booking experience. AI will really assist customers in planning vacations. I can’t wait for this to be optimized. Booking is the world leader in online travel and related services. One of the best Internet acquisitions ever was when Priceline (PCLN) acquired Bookings BV in 2005, which got PCLN a piece of the underdeveloped European online travel industry. BKNG went on to become a catalyst in two years, from 2005 Q3 to 2007 Q3. Domestic qtrly bookings grew from $378 million to $602 million (+59%), while International revenue ballooned from $156 million to $758 million (+380%). In February 2018, PCLN formally changed its name (and stock symbol) to Booking Holdings (BKNG). Bookings was the #1 downloaded travel app in the world in 2023. Booking intends to integrate AI to its platforms to further drive operations efficiency. The company’s service offerings include:
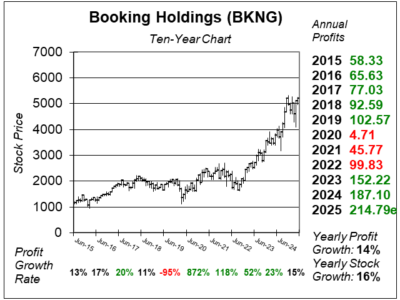
I’ve owned Booking (formerly Priceline) since 2006 and profits hit record highs every year up until 2019. In 2020, COVID-19 hampered travel world wide and profits went down. BKNG currently has an Estimated Long-Term Growth rate of 16%. Management repurchased $6 billion in stock during 2024 and paid $1.2 billion in dividends. BKNG pays a quarterly dividend of $8.75, or $35 a year. The stock is part of the Conservative Growth Portfolio. I think its a mid-teens grower long-term. |
One Year Chart |
 This stock is hitting resistance here. This is All-Time high territory. The P/E of 24 is reasonable. My Fair Value is a P/E of 27. But I think the stock might someday get a P/E closer to 30. The Est. LTG decreased from 16% last qtr to 15% this quarter. I consider this company to be a mid-teens grower, so this current figure is accurate. BKNG delivered 22% profoit growth last qtr which was way above estimates of -14%. So maybe the company can surpass 320% growth this qtr? |
Earnings Table |
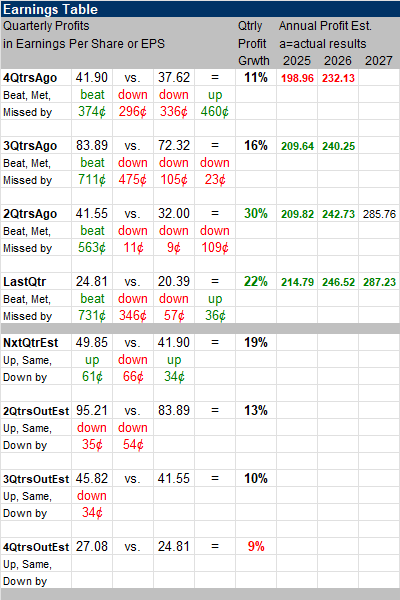 Last qtr, Booking delivered 22% profit growth and beat expectations of -14% growth. Revenue increased 8% year-over-year and beat expectations of 4%. Total gross bookings increased 7%. Air tickets surged 45%, while room nights sold grew 7%. M0bile bookings represented mid-50% of total room nights, up from low-50% in 2023. In terms of units sold during the qtr:
Alternative accommodations grew 12% year-over-year and now account for 37% of all room nights on Booking.com, reflecting the company’s push to give travelers more flexible options. Annual Profit Estimates increased this qtr. Qtrly Profit Estimates are 19%, 13%, 10%, and 9% profit growth in the next 4 qtrs. Analysts believe BKNG revenue will climb 12% next qtr. |
Fair Value |
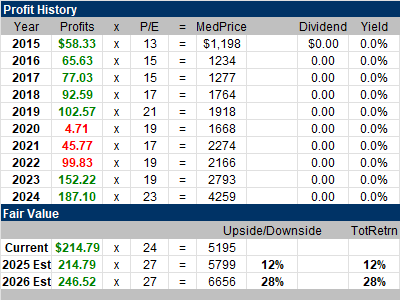 Notice how low the P/E has been over the years. It was around 15 ten years ago. The stock has recently gotten more respect. I’ve owned this stock for almost two decades, and the stock has gotten little respect during that time. This quarter the stock sells for 24x 2025 profit estimates. My Fair Value P/E is 27x estimates, which equates to $5799, giving the stock upside of 12%. |
Bottom Line |
 Booking (BKNG) was once rapid growth stock that has since evolved into a Blue Chip stock. I originally bought the stock for investors in May 2006 $29, sold at $83 in March 2009 then jumped back in during May 2009 at $105 and have stuck with it since. The stock was in my Growth Portfolio for much of this time, then I moved it into the Conservative Portfolio when it seemed like profit growth was simmering down from the 15% range to the 12% range. Booking is a sleek machine pumping out profits. It’s a good stock to buy-and-hold and I feel there’s good upside at this time. BKNG moves up from 11th to 8th in the Conservative Growth Portfolio Power Rankings. |
Power Rankings |
Growth Stock Portfolio
N/AAggressive Growth Portfolio N/AConservative Stock Portfolio 8 of 20 |
