Stock (Symbol) |
Amazon.com (AMZN) |
Stock Price |
$2923 |
Sector |
| Retail & Travel |
Data is as of |
| February 11, 2022 |
Expected to Report |
| April 27 |
Company Description |
 Amazon.com, Inc. (Amazon.com) is an e-commerce company. The Company’s products are offered through consumer-facing Websites, which include merchandise and content that it purchases for resale from vendors and those offered by third-party sellers. It also manufactures and sells electronic devices, including Kindle e-readers, Fire tablets, Fire TVs, Echo and Fire phones. Amazon.com operates in two segments: North America and International. The North America segment focuses on retail sales earned through North America-focused Websites. It serves developers and enterprises through Amazon Web Services (AWS). It serves authors and independent publishers with Kindle Direct Publishing. Source: Thomson Financial |
Sharek’s Take |
 Amazon (AMZN) continues to see cost pressure from labor supply shortages and inflationary pressures, as profits declined 59% last qtr. But a bright spot in the results was Amazon Web Services (AWS) which delivered outstanding sales growth of 40%. Overall, AMZN delivered 9% revenue growth, including 9% growth in North America retail sales, 3% growth in International retail, and 40% in AWS. Investors liked the report, and sent shares of AMZN higher after the news. This was a BIG report, as the stock market was in a deep decline, and this stock climbing was a breath of fresh air that perhaps stopped the market’s decline. But since then, the company has had to deal with higher gasoline prices, and that could wreck profits this qtr. Founded in 1994, Amazon serves customers through its online and physical stores with a focus on selection, price, and convenience. The company with more than 1 million full-time and part-time employees work to deliver hundreds of millions of unique products that are sold by Amazon itself and third party sellers. Amazon Web Services, AMZN’s cloud platform, was the company’s best operating segment last qtr, with a revenue growth of 40% year-over-year last qtr versus 9% growth in the North America retail sales and 3% growth in International sales. Here’s some other info about the company:
In 2021, Operating Income in North America fell to $7.3 billion from $8.7 billion in 2020, while International fell from $717 million to -$924 million, as AWS rose to $18.5 billion from $113.5 billion a year earlier. So AWS is the only division that’s doing well. Meanwhile, 2022 profit estimates have fallen from $72.09 to $48.82 during the past four qtrs. Still, the stock has a robust Estimated Long-Term Growth Rate of 35% per year, which is one of the highest amongst large enterprises. With gasoline prices jumping this qtr, I imagine the retail side of the business will deliver poor results. I’m afraid the company is going to miss profit estimates next qtr. Amazon is part of my Conservative Growth Portfolio and Growth Portfolio. I will sell the shares from both portfolios today as I think profits will be hurt by higher gas prices. This week, management announced a $10 billion share buyback as well as a 20-for-1 stock split. That gave temporary boost to the stock, but the company has a market cap of $1.5 trillion so a $10 billion buyback isn’t gonna help much. |
One Year Chart |
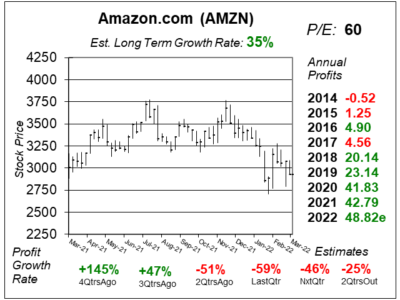 This stock is in a downtrend, and with a P/E of 60 the shares could go lower. AMZN has had a lofty P/E for as long as I can remember. Maybe now is the time the P/E falls to a more reasonable 45? That would be a stock price of around $2200. OR the P/E could stay the same (60) and profits could decline to $36.66 this year and that would also get us to a $2200 stock. AMZN has an Estimated Long-Term Growth Rate of 35% which is outstanding. This figure was 36% last qtr. Note Estimates show profit growth has slowed in a big way. |
Earnings Table |
 Last qtr, Amazon delivered -59% profit growth and beat estimates of -73%. Revenue increased 9%, over last year. Third-party sellers and products accounted for 56% of units sold. Top-selling items during the holiday season were apparel, beauty, home, and toys. Segment growth was:
In last qtr’s earnings press release, the company stated it made $14.3 billion in profit or $27.75 per share vs. $14.09 in the year-ago period. But that includes $11.8 billion in non-operating income from its Rivian Automotive stock investment. Note our profit from last qtr doesn’t include the Rivian “gain”. Annual Profit Estimates declined this qtr. Qtrly profit Estimates are for -46%, -25%, 112%, and 162% profit growth the next 4 qtrs. For next qtr, management expects qtrly sales to grow between 3%-8% to around $120 billion It will also incur affected by higher operational costs from labor, productivity losses, and raw material inflation. |
Fair Value |
 The past four qtrs, this stock has had a P/E of 63, 58, 60, and now 66. This qtr the P/E is 60. My Fair Value P/E remains at 65. Last qtr, my 2022 Fair Value was 65 x $51.50 = $3348. This qtr, my Fair Value is 65 x $48.06 = $3124. These additional expenses have hurt the stock’s 2022 prospects. |
Bottom Line |
 Amazon (AMZN) has been a terrific stock to own this past decade. Now the stock has turned lower, and that trend could continue. Amazon has some tough quarters ahead, and I believe profit estimates will decline this qtr with gasoline prices surging higher. Thus, AMZN stock might decline in a big way after the company reports earnings. In addition, the stock market is extremely weak and looks to go 10% to 15% lower. Big stocks like Amazon could take the brunt of the hit. AMZN will be sold from the Growth Portfolio and Conservative Portfolio. As a conservative stock, this doesn’t give me much certainty with profit estimates. And as a growth stock, profit growth is negative while annual estimates trend down. This company has had profits decline more than 50% the past two qtrs. And with a P/E of 60, AMZN is expensive. |
Power Rankings |
Growth Stock Portfolio
19 of 33Aggressive Growth Portfolio N/AConservative Stock Portfolio 8 of 37 |
