Stock (Symbol) |
Tractor Supply (TSCO) |
Stock Price |
$82 |
Sector |
| Retail & Travel |
Data is as of |
| February 11, 2016 |
Expected to Report |
| Apr 20 – Apr 25 |
Company Description |
 Tractor Supply Company is an operator of rural lifestyle retail stores in the United States. The Company focuses on supplying the lifestyle needs of recreational farmers and ranchers, as well as tradesmen and small businesses. As of December 27, 2014, it operated 1,382 retail stores in 49 states under the names Tractor Supply Company, Del’s Feed & Farm Supply and HomeTown Pet. It also operates a Website under the name TractorSupply.com. It offers a portfolio of products, which include equine, livestock, pet and small animal products; hardware, truck, towing and tool products; seasonal products, including lawn and garden items, power equipment, gifts and toys; work/recreational clothing and footwear, and maintenance products for agricultural and rural use. Its products are offered under various brands, which include 4health, Blue Mountain, Countyline, Equistages, Groundwork, Huskee, JobSmart, Dumor, C.E. Schmidt, Paws & Claws, Producer’s Pride and Redstone, among others. Source: Thomson Financial |
Sharek’s Take |
 Last qtr, Tractor Supply (TSCO) was expected to have profit growth of $0.91 vs. $0.81 = 12% but missed estimates by 9 cents and delivered just 1% profit growth. Investors just shrugged off the miss, blaming bad weather. The stock remains in the $80s where it has for much of the last year. Tractor Supply is the largest operator of rural lifestyle retail stores in the United States, servicing farmers, ranchers and small businesses. The combination of store growth of 7% to 8% per year, expanding profit margins, and same-store sales of 3% to 4% could mean profit growth in the high-teens per year. TSCO also pays a dividend of around 1% and management buys back stock. 2016 is expected be a good one as the company grows its Purina selection, expands its outdoor recreational equipment, and rolls out its loyalty club program. Management sees the chain growing from 1,500 locations to 2,500 long-term as it expands from the Midwest and South to the West and populated Northeast. I own TSCO in the Conservative Portfolio, but am dying to buy it for the Growth Portfolio on a dip. I want it to be a dip because the stock’s fairly valued here. The stock market had its worst starts to a year during January & February, but TSCO barely dropped 10%. It’s a quality stock, and investors didn’t sell. |
One Year Chart |
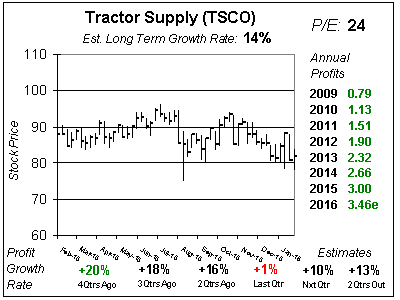 Last qtr I thought investors should be patient and get TSCO at $80. Then it dipped and I didn’t buy it for clients in the Growth Portfolio. But it was a crazy market, that could perhaps develop into a Bear Market and you don’t want to buy little dips in Bear Markets — especially when the P/E is almost double the Est. LTG. And I knew the company was going to miss because it prewarned. The bad news caused NxtQtr’s estimates fell by 3 cents, but the other qtrs remained the same. Also, 2016’s est fell from $3.58 to $3.46 and 2017’s from $4.10 to $3.97. Profits are expected to climb 10%, 13% and 14% the next 3 qtrs. |
Fair Value |
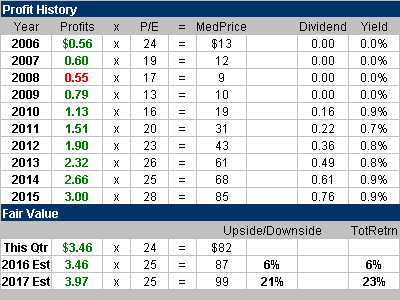 TSCO was a little overvalued a year ago, when it had a P/E of 27. My Fair Value on this stock is 25x earnings. Bear in mind these charts were done on 2/11 when TSCO was $81. Today, 3/2, the stock is $87 after a swift move up in a rising stock market. The stock’s sitting right at my Fair Value. |
Bottom Line |
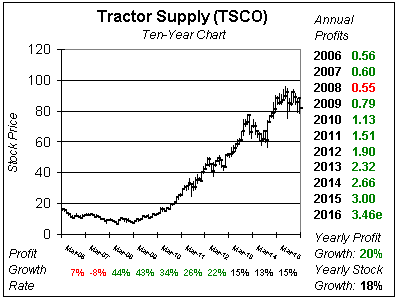 Tractor Supply’s mix of more stores, higher sales per store, stock buybacks and dividends makes this a quality selection for conservative growth accounts. But the stock market’s correction during Jan & Feb has left other stocks on sale, so I don’t see the value here in buying for “sticker price”. I continue to think growth investors in search of more potential should be patient and try to get in around $80. TSCO ranks 14th in the Conservative Growth Portfolio Power Rankings and is on the radar for the Growth Portfolio. |
Power Rankings |
Growth Stock Portfolio
N/AAggressive Growth Portfolio N/AConservative Stock Portfolio 14 of 36 |
